Missing a payment can have consequences. Here’s how to protect yourself.
Some months, no matter how carefully you plan your money, it runs out too fast.
Petrol prices rise again. The kids need something extra for school. Or there’s a doctor’s bill that must be paid and before you know it, you’re worried about making your next debt review payment.
If this sounds familiar, the first thing to know is that missing a payment can put your debt review agreement at risk.
Remember, debt review helps South Africans struggling to pay their debts through a more affordable repayment plan.
A debt counsellor works with credit providers to arrange repayments, and these arrangements may also become part of a court order.
The bottom line is that missing debt review payments can do more than just put you behind; they can also remove your legal protection against debt enforcement.
Don’t assume you have a grace period. There isn’t one that automatically applies to every debt review agreement.
But at the same time, one missed payment doesn’t automatically mean you’re out of debt review or heading to court.
The biggest risk is legal action, not a fixed penalty
Depending on your circumstances, a missed payment during debt review could eventually lead to a summons, a court judgment against you, or the loss of an asset, such as your car or home, through repossession.
However, South African debt review termination follows specific legal rules.
And missing a payment doesn’t automatically cancel your debt review status. Credit providers must follow the legal process that applies to your situation.
Your first move should be to speak up
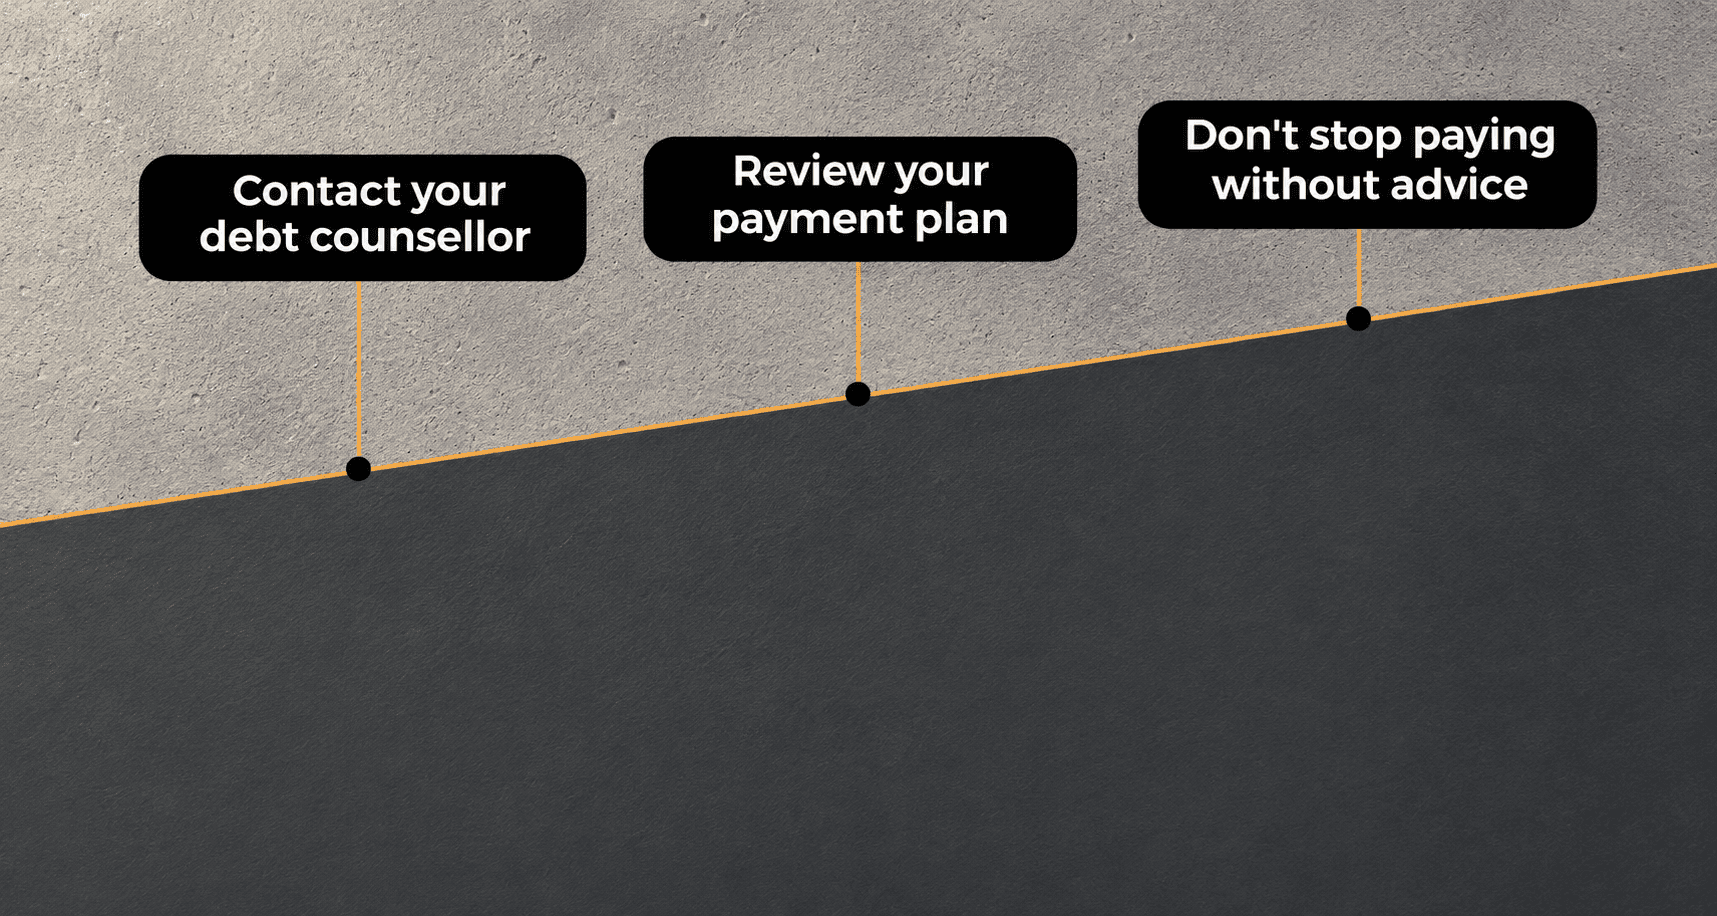
If you’re having debt review payment plan problems, don’t wait until you’ve skipped several payments. Start by contacting your debt counsellor. The sooner you do this, the better.
Explain what’s happened and why you’re struggling. If your income has dropped or you’ve had unexpected expenses, share any documents that help explain your situation.
Your debt counsellor can then review your circumstances and explain whether you can change your payment plan. Formal changes may need court approval.
It’s also worth checking whether you have credit life insurance that could help if you’ve been retrenched or become unable to work, depending on your policy.
Whatever you do, don’t just stop paying or make your own arrangements without advice.
Small money habits can help you stay on track
Staying on track with debt review also means looking ahead to avoid the same problem next month.
Start with your monthly budget. Check that your payment date works with your salary date. Keep an eye on expenses that change from month to month.
And if possible, set a little money aside for emergencies. Every small amount can help.
Most importantly, stay in touch with your debt counsellor. The sooner you raise a problem, the more opportunity you may have to find a solution.
Debt review is meant to help you work towards a better financial future. Don’t let one difficult month undo the progress you’ve made.
Worried about making your debt review payments?
Don’t wait for the problem to grow. Speak to National Debt Counsellors (NDC) for guidance on your options and the next steps.
You can also get your free Finance365 credit report to check what’s recorded against your name.